
Best Personal Loan Settlement Agency in Kolkata – UPTURN
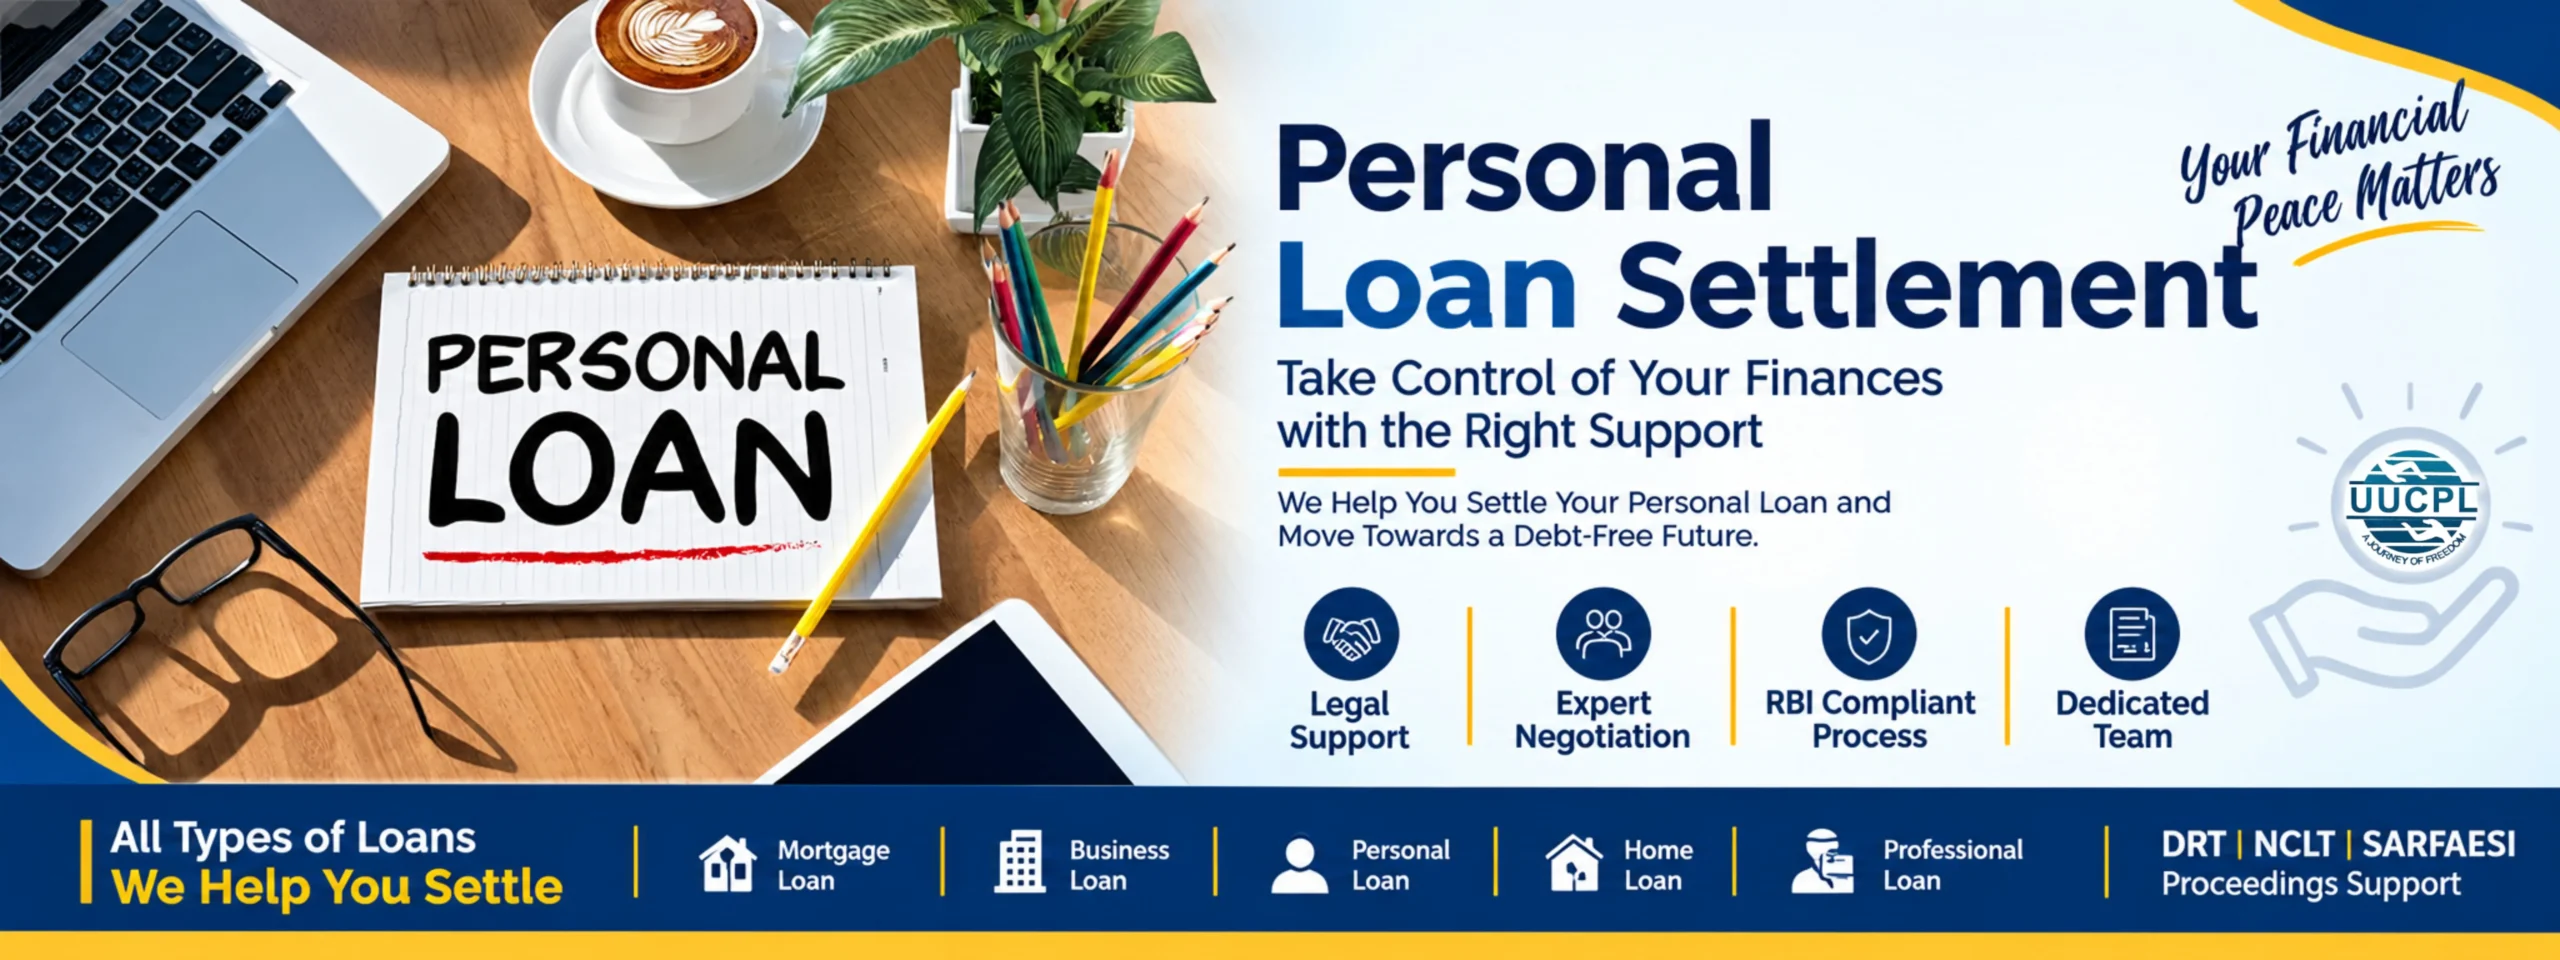
Are you struggling with an overdue personal loan and looking for reliable Personal Loan Settlement assistance in Kolkata? Upturn United Consultancy Pvt. Ltd. provides professional guidance and negotiation support for borrowers facing financial difficulties and personal loan defaults.
Personal Loan Settlement is a process where a borrower and lender negotiate to resolve an outstanding loan for an agreed settlement amount, subject to the lender’s approval and applicable policies. The process can involve reviewing the borrower’s financial circumstances, communicating with the lender, negotiating settlement terms, and completing the required documentation.
At Upturn, our team of legal and financial professionals provides support throughout the Personal Loan Settlement process. We help borrowers understand their available options and communicate with lenders regarding settlement or repayment arrangements.
If you are searching for a Personal Loan Settlement Agency in Kolkata, Personal Loan Settlement Company, or Personal Loan Settlement Services near me, it is important to understand the process, documentation, credit-reporting implications, and legal considerations before proceeding.
What Is Personal Loan Settlement?
Personal Loan Settlement refers to an arrangement between a borrower and lender to resolve an outstanding personal loan by paying an amount mutually accepted by the lender, subject to its internal policies and approval.
Personal loans are generally unsecured loans, meaning they are not backed by a specific property or other secured asset. However, failure to repay a personal loan can still result in recovery actions, credit-reporting consequences, legal proceedings, and other steps permitted under applicable law.
A settlement is not the same as simply closing a loan through regular repayment. Where a lender accepts less than the total outstanding amount as a compromise settlement, the account may be reported differently from a normally repaid and closed loan. Borrowers should therefore understand the potential effect on their credit profile before agreeing to any settlement.
Why Do Borrowers Consider Personal Loan Settlement?
Borrowers may consider Personal Loan Settlement when they are facing genuine financial hardship and are unable to continue servicing the outstanding debt according to the original repayment schedule.
Common circumstances may include:
- Loss or reduction of income
- Business or professional financial difficulties
- Multiple outstanding loans
- Accumulated EMIs and interest
- Unexpected financial obligations
- Prolonged loan default
- Difficulty managing several creditors
- Recovery notices or collection activity
Every case is different, and settlement is not automatically available. The lender generally evaluates the borrower’s circumstances and decides whether a settlement proposal can be considered.
Personal Loans: A Legal Overview
Personal loans are generally unsecured. This makes the legal and recovery process different from that applicable to secured loans such as home loans or mortgage loans.
Because a personal loan normally does not involve a mortgage over a specific property, SARFAESI proceedings for taking possession of secured property generally do not apply to an ordinary unsecured personal loan. However, this does not mean that a borrower has no legal obligations.
Depending on the circumstances, a lender may pursue lawful recovery measures, including contractual remedies and court proceedings.
What Is a Personal Loan Agreement?
A personal loan agreement is a legally binding contract between the borrower and lender. Depending on the lender and product, it generally contains provisions relating to:
- Loan amount
- Interest rate
- Loan tenure
- EMI repayment schedule
- Late-payment charges
- Default provisions
- Auto-debit or e-NACH mandates
- Assignment of debt
- Collection and recovery provisions
- Jurisdiction
- Dispute-resolution mechanisms
Understanding the terms of the original loan agreement is an important part of evaluating a Personal Loan Settlement case.
Laws and Regulations Relevant to Personal Loan Default in India
Several laws and regulatory frameworks may become relevant to personal loan disputes and recovery, depending on the circumstances.
Indian Contract Act, 1872
The loan agreement creates contractual obligations between the lender and borrower. The terms of the agreement may determine repayment obligations, default conditions and available contractual remedies.
Code of Civil Procedure, 1908
A lender may pursue civil recovery proceedings where legally applicable if an outstanding debt remains unpaid.
Negotiable Instruments Act, 1881
Where a cheque issued toward a legally enforceable debt is dishonoured, Section 138 of the Negotiable Instruments Act may become relevant, subject to fulfilment of the statutory requirements.
RBI Recovery and Fair-Practice Requirements
Banks and regulated lending entities must follow applicable RBI requirements relating to recovery practices and customer treatment. Digital lending arrangements are also subject to applicable RBI regulatory requirements.
Credit Information Reporting
Loan defaults and repayment status can be reported to credit information companies in accordance with applicable rules. Borrowers should understand how a settlement may be reflected in their credit history before accepting a settlement proposal.
What Happens If You Don’t Pay a Personal Loan?
The exact process depends on the lender, loan agreement, amount involved and circumstances of the default. Generally, a borrower may experience the following stages:
1. Payment Reminders
The lender may initially send payment reminders through calls, messages, emails or other permitted communication channels.
2. Recovery Communication
If the account remains overdue, the lender may increase recovery communication or assign the account to an authorised recovery agency.
3. Legal Notice
In appropriate circumstances, a lender may issue a formal legal notice demanding repayment.
4. Civil Recovery Proceedings
Where legally appropriate, the lender may initiate civil recovery proceedings to recover the outstanding amount.
5. Cheque Dishonour Proceedings
If a cheque issued toward a legally enforceable debt is dishonoured, proceedings under Section 138 of the Negotiable Instruments Act may arise if the statutory requirements are satisfied.
6. Credit Bureau Reporting
Payment defaults may be reported to credit information companies, potentially affecting future access to credit.
For borrowers facing prolonged financial difficulty, early professional assessment may help them understand whether Personal Loan Settlement, restructuring, repayment planning or another lawful option is appropriate.
Can Personal Loan Default Lead to Arrest?
A personal loan default is generally a civil debt matter and does not automatically mean that a borrower will be arrested merely because an EMI has not been paid.
However, borrowers should not assume that every situation involving a loan is identical. Separate legal issues may arise depending on the facts, such as cheque dishonour proceedings or allegations of fraud.
If you receive a legal notice, court summons or any other formal communication, it is advisable to obtain appropriate legal advice rather than ignoring it.
Can Recovery Agents Contact Your Employer or Family?
Recovery activities must comply with applicable regulatory and legal requirements. Lenders and their authorised recovery agents should not use harassment, intimidation, abusive conduct or inappropriate disclosure of a borrower’s financial information as a recovery method.
For regulated entities, applicable RBI instructions govern the conduct of recovery agents and customer communication.
If you believe that a recovery agent has engaged in inappropriate conduct, preserve call records, messages and other evidence and consider raising the matter through the lender’s grievance-redressal mechanism or other appropriate regulatory/legal channels.
Borrower Rights During Personal Loan Settlement
Borrowers facing personal loan default have important rights and responsibilities.
Right to Understand the Outstanding Amount
You can seek information about the outstanding principal, interest, charges and other applicable amounts.
Right to Review Settlement Terms
Before accepting a settlement proposal, carefully review the settlement amount, payment deadline, documentation and consequences of non-payment.
Right to Fair Recovery Practices
Recovery communication should comply with applicable legal and regulatory requirements. Harassment, threats and abusive behaviour are not appropriate recovery methods.
Right to Dispute Incorrect Credit Information
If your credit report contains inaccurate information, you can raise a dispute through the relevant credit information company and lender.
Right to Seek Legal Advice
Where notices, court proceedings, cheque dishonour matters or other legal issues are involved, borrowers may seek advice from a qualified legal professional.
What Is One-Time Settlement (OTS) in Personal Loan?
A One-Time Settlement (OTS) is a negotiated arrangement under which a lender agrees to accept a specified amount to resolve an outstanding loan, subject to its applicable policy and approval process.
An OTS proposal does not guarantee that a lender will waive a particular amount. The lender may consider factors such as:
- Outstanding dues
- Borrower’s financial circumstances
- Security, where applicable
- Age of the default
- Repayment capacity
- Recovery prospects
- Applicable lender policy
A borrower should obtain the settlement terms in writing and make payment only through verified and authorised channels.
Personal Loan Settlement and CIBIL Score
One of the most important considerations before choosing Personal Loan Settlement is its potential impact on your credit history.
If a lender accepts an amount lower than the total contractual dues as a settlement, the account may be reported as “Settled” rather than “Closed”, depending on the lender’s reporting and applicable credit-information practices.
A settled status can affect how future lenders assess your credit application. Therefore, borrowers should understand the potential credit consequences before accepting a settlement.
Settlement should be considered as a financial resolution option, not as a guaranteed method of improving a credit score.
Personal Loan Settlement vs Loan Restructuring
Personal Loan Settlement and loan restructuring are different processes.
Personal Loan Settlement:
The lender agrees to resolve the outstanding account for an approved settlement amount, which may be lower than the total contractual dues.
Loan Restructuring:
The lender modifies repayment terms, such as the repayment schedule or other applicable terms, while the underlying debt generally continues to be repaid.
The appropriate option depends on the borrower’s financial circumstances, lender policy and the status of the loan.
How Upturn Helps With Personal Loan Settlement
At Upturn United Consultancy Pvt. Ltd., we provide advisory and negotiation support to borrowers dealing with personal loan defaults and financial difficulties.
Our support may include:
- Understanding your outstanding loan position
- Reviewing relevant loan and recovery documents
- Assessing the settlement-related circumstances
- Communicating and negotiating with lenders
- Supporting settlement proposal discussions
- Assisting with documentation
- Explaining possible credit-reporting implications
- Providing guidance regarding recovery notices and related proceedings
Our objective is to help borrowers understand their available options and approach the lender through a structured and documented process.
A Personal Loan Settlement is subject to the lender’s approval and applicable policies. We do not guarantee a specific settlement amount or outcome.
Why Choose Upturn for Personal Loan Settlement in Kolkata?
If you are searching for a Personal Loan Settlement Agency in Kolkata, professional experience and transparent communication are important considerations.
Upturn United Consultancy Pvt. Ltd. provides loan settlement advisory and negotiation support with a team that includes legal and financial professionals.
We assist borrowers with different types of loan-related matters and help them understand the documentation, negotiation process and possible consequences before proceeding.
Our approach focuses on:
- Professional guidance
- Transparent communication
- Document-based assessment
- Negotiation support
- Legal and financial coordination
- Practical resolution strategies
Frequently Asked Questions About Personal Loan Settlement
What is Personal Loan Settlement?
Personal Loan Settlement is a negotiated arrangement in which a lender agrees to accept an approved settlement amount to resolve an outstanding personal loan, subject to its policies and approval.
Is Personal Loan Settlement legal in India?
Settlement of an outstanding loan can be legally permissible when it is mutually agreed upon and documented between the borrower and lender. The exact terms and reporting consequences depend on the lender and applicable rules.
Can I settle my personal loan after default?
A borrower may approach the lender for a settlement after default, but approval is not automatic. The lender evaluates the proposal according to its policies and circumstances.
Will Personal Loan Settlement affect my CIBIL score?
A settlement may affect your credit history. If the lender reports the account as “Settled” rather than “Closed,” it can influence how future lenders assess your creditworthiness.
Can I settle a personal loan without going to court?
In many cases, borrowers and lenders may negotiate a settlement without court proceedings. However, if legal proceedings have already started, the appropriate legal process should be followed.
Can a personal loan lender seize my property?
An ordinary unsecured personal loan does not generally provide the lender with SARFAESI-based possession rights over a specific property. However, a lender may have other lawful recovery remedies, including court proceedings where applicable.
Can recovery agents threaten borrowers?
Recovery agents should follow applicable legal and regulatory requirements. Harassment, threats and abusive recovery practices are not appropriate.
Does Upturn provide loans?
No. Upturn does not provide loans. We provide advisory and negotiation support related to loan settlement and related debt-resolution matters.
Get Professional Personal Loan Settlement Assistance in Kolkata
If you are struggling with overdue EMIs, recovery calls, legal notices or increasing personal loan debt, understanding your options early can help you make informed financial decisions.
Upturn United Consultancy Pvt. Ltd. provides Personal Loan Settlement advisory and negotiation support for eligible borrowers in Kolkata and across India.
Important: Upturn is an independent consultancy and is not a bank, NBFC or lender. We do not provide loans. Personal Loan Settlement is subject to lender approval, applicable policies and the individual facts of each case.
Contact Upturn for a consultation regarding your Personal Loan Settlement requirements.