
Mortgage Loan Settlement in India: Process, Benefits & Legal Options
Struggling with an outstanding mortgage loan or Loan Against Property (LAP) can create significant financial and legal pressure. Mortgage Loan Settlement may be an option for borrowers who are facing genuine financial difficulties and are unable to repay their outstanding dues according to the original repayment schedule. The Mortgage Loan Settlement Process generally involves reviewing the borrower’s financial circumstances, assessing the outstanding loan and security, and negotiating with the lender for a mutually acceptable settlement arrangement.
A professional Mortgage Loan Settlement Agency may provide advisory, documentation, and negotiation support to borrowers dealing with banks or financial institutions. Whether the loan is a Mortgage Loan, Loan Against Property (LAP), Business Loan Against Property, or another secured loan, settlement requires careful consideration of the lender’s policies, the value of the mortgaged property, outstanding dues, repayment capacity, and the stage of recovery proceedings.
If you are searching for Mortgage Loan Settlement in India, LAP Loan Settlement, or Loan Against Property Settlement, it is important to understand the legal process before taking any decision. This guide explains the Mortgage Loan Settlement Process, relevant laws, borrower rights, SARFAESI proceedings, DRT remedies, and other legal options available in India.
What Is Mortgage Loan Settlement?
Mortgage Loan Settlement refers to a negotiated arrangement between a borrower and lender for resolving outstanding dues on a mortgage-backed loan, subject to the lender’s applicable policies and approval procedures.
A mortgage loan is generally secured against immovable property. A common example is a Loan Against Property (LAP), where an existing residential, commercial, or other eligible property is offered as security for funds raised for business, personal, or other permitted purposes.
Because a mortgage loan is secured by property, default can result in recovery and enforcement proceedings against the mortgaged asset. Therefore, borrowers facing repayment difficulties may explore Mortgage Loan Settlement Options before the recovery process progresses further.
Settlement is not an automatic waiver of the loan. Whether a lender accepts a settlement proposal depends on its applicable policy, the borrower’s circumstances, outstanding dues, security value, repayment capacity, and other relevant factors.
What Is a Loan Against Property (LAP) Settlement?
Loan Against Property Settlement, commonly called LAP Loan Settlement, involves discussions between the borrower and lender regarding resolution of outstanding dues on a loan secured by property.
Depending on the lender’s policy and the circumstances of the case, the settlement process may involve:
- Reviewing the total outstanding loan amount.
- Assessing the borrower’s financial hardship and repayment capacity.
- Reviewing the current status and value of the mortgaged property.
- Examining notices or recovery proceedings already initiated.
- Preparing and submitting a settlement proposal.
- Negotiating repayment or settlement terms with the lender.
- Obtaining appropriate approval from the lender.
- Completing the agreed payment and documentation requirements.
Legal Framework Governing Mortgage Loan Settlement in India
Several laws and regulatory frameworks can become relevant to Mortgage Loan Settlement in India, depending on the nature of the loan and recovery action.
Transfer of Property Act, 1882
The Transfer of Property Act, 1882 contains provisions relating to mortgages and the rights and obligations associated with mortgaged immovable property.
Indian Contract Act, 1872
The underlying loan agreement is generally governed by contractual principles, including the obligations of the borrower and lender.
SARFAESI Act, 2002
The Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 may allow eligible secured creditors to enforce security interests subject to the Act and applicable requirements.
For borrowers facing LAP Loan Recovery or mortgage enforcement, understanding SARFAESI proceedings is particularly important.
Recovery of Debts and Bankruptcy Act, 1993
The Recovery of Debts and Bankruptcy Act provides the framework for proceedings before the Debt Recovery Tribunal (DRT) in applicable cases.
Registration Act, 1908
The Registration Act may become relevant to registered mortgage documentation and registration requirements.
RBI Guidelines and Fair Practices Requirements
Applicable RBI directions and fair-practice requirements can govern various aspects of lending, borrower communication, recovery practices, and grievance handling, depending on the lender and nature of the facility.
Key Factors Considered in Mortgage Loan Settlement
Before approaching a lender for Mortgage Loan Settlement, borrowers should understand the factors that may influence a settlement proposal.
1. Outstanding Loan Amount
The total principal, interest, charges, and other applicable dues may be reviewed while preparing a settlement proposal.
2. Value of the Mortgaged Property
The lender may consider the value and enforceability of the security when assessing recovery prospects.
3. Financial Hardship
The borrower’s current financial circumstances and reasons for repayment difficulties may be relevant to the lender’s assessment.
4. Repayment Capacity
The lender may consider the borrower’s present and expected ability to make payment.
5. Recovery Status
The stage of recovery proceedings can affect the available options. A case involving a recent default may be at a different stage from one where a SARFAESI notice, possession notice, or auction notice has already been issued.
6. Recovery Prospects
The lender may consider the likely recovery from different available courses of action when evaluating a settlement proposal.
Mortgage Loan Settlement Process in India
The Mortgage Loan Settlement Process can vary depending on the lender, loan agreement, security, outstanding dues, and recovery stage. A typical process may include:
Step 1: Review the Loan Account
The borrower should collect and review the loan agreement, account statement, repayment history, outstanding balance, and relevant correspondence.
Step 2: Assess the Financial Situation
The borrower’s current income, liabilities, financial hardship, repayment capacity, and available funds should be evaluated.
Step 3: Review the Mortgage and Property Documents
The title documents, mortgage documentation, property details, valuation records, and other relevant documents should be examined.
Step 4: Check the Recovery Status
It is important to identify whether the account has been classified as an NPA and whether any demand notice, possession notice, auction notice, or other recovery action has been issued.
Step 5: Prepare a Settlement Proposal
A borrower may submit a proposal explaining the circumstances and the amount that can realistically be offered, subject to the lender’s applicable settlement policy.
Step 6: Negotiate With the Lender
The lender may review the proposal and negotiate the terms. Any settlement should be properly documented and approved by the authorised authority of the lender.
Step 7: Complete the Agreed Payment
Once the settlement terms are formally accepted, the borrower must comply with the agreed payment schedule and other conditions.
Step 8: Obtain Settlement Documentation
After completing the agreed settlement, borrowers should obtain appropriate documentation from the lender confirming the status of the account and release of security, wherever applicable.
Mortgage Loan Default and SARFAESI Process
When a secured loan account becomes an NPA and the applicable legal requirements are satisfied, a lender may initiate enforcement proceedings under the SARFAESI Act, 2002.
A simplified sequence may include:
- NPA classification — generally after the applicable regulatory period of overdue status.
- Section 13(2) demand notice — a statutory demand notice may provide 60 days for payment of the specified dues.
- Borrower’s representation or objection — the borrower may submit objections or representations in accordance with Section 13(3-A).
- Enforcement measures — subject to applicable legal requirements, the secured creditor may take measures under Section 13(4).
- Possession and sale proceedings — depending on the case, possession and sale/auction proceedings may follow.
- DRT remedy — an aggrieved borrower may approach the Debt Recovery Tribunal under the applicable provisions of the SARFAESI Act.
Because the exact procedure depends on the facts of the case, borrowers should review the relevant notices and deadlines carefully.
Can Mortgage Loan Settlement Be Done After a SARFAESI Notice?
A Mortgage Loan Settlement after SARFAESI Notice may still be explored, depending on the circumstances and the lender’s applicable policy.
Receiving a Section 13(2) demand notice does not itself mean that the property has immediately been sold. The borrower may have rights and remedies available under the SARFAESI framework, including the ability to submit representations or objections where applicable.
At the same time, borrowers should not ignore statutory notices or assume that settlement discussions automatically stop recovery proceedings. Legal and settlement options may need to be considered together.
Borrower Rights in Mortgage Loan Recovery
Borrowers dealing with Mortgage Loan Recovery should understand the documentation and legal protections applicable to their case.
Depending on the circumstances, relevant rights may include:
- Receiving the applicable loan and mortgage documentation.
- Receiving statutory notices required under applicable law.
- Submitting representations or objections where the law provides for them.
- Challenging certain enforcement measures before the appropriate legal forum.
- Seeking information relating to the proposed sale or auction as permitted under applicable rules.
- Redeeming the secured property where the applicable law permits redemption.
- Receiving any surplus amount remaining after lawful adjustment of the lender’s dues and applicable costs, where applicable.
- Protection against unlawful or coercive recovery practices.
Mortgage Loan Settlement vs Loan Restructuring
Mortgage Loan Settlement and Mortgage Loan Restructuring are not the same.
In restructuring, the existing loan is generally modified through revised repayment terms, such as changes to the repayment schedule or other applicable terms, while the borrower continues to repay the loan according to the revised arrangement.
In settlement, the lender and borrower agree on terms for resolving the outstanding account, subject to the lender’s approval and applicable policy.
The financial, legal, and credit-reporting consequences can differ between the two options. Borrowers should therefore understand the specific terms before accepting either arrangement.
Benefits and Considerations of Mortgage Loan Settlement
A successful Mortgage Loan Settlement may help resolve an outstanding secured loan through a negotiated arrangement approved by the lender. Depending on the case, it may also help borrowers address recovery proceedings and work toward resolution of the outstanding account.
However, settlement also involves important considerations. A settlement may have consequences for the borrower’s credit history and future access to credit, depending on how the lender reports the account. The borrower should also understand all payment obligations, documentation requirements, and the status of the mortgaged property before proceeding.
Settlement should therefore be considered based on the borrower’s circumstances rather than treated as an automatic alternative to repayment.
Frequently Asked Questions About Mortgage Loan Settlement
What happens if I default on a mortgage loan or Loan Against Property?
If a secured loan remains overdue and meets the applicable regulatory criteria for NPA classification, the lender may initiate recovery measures. Where SARFAESI applies and its requirements are satisfied, the lender may issue a Section 13(2) demand notice and subsequently take further enforcement action.
Can I settle my mortgage loan after receiving a SARFAESI notice?
Settlement discussions may still be possible after a SARFAESI notice, subject to the lender’s policy and the circumstances of the case. Borrowers should also address statutory deadlines and legal remedies separately rather than relying only on settlement negotiations.
What is the difference between mortgage loan settlement and LAP loan settlement?
Mortgage Loan Settlement is a broad term for settlement of a mortgage-backed loan, while LAP Loan Settlement specifically refers to settlement of a Loan Against Property. The applicable process depends on the loan agreement, lender, property security, and recovery status.
Can I settle a Loan Against Property before auction?
A borrower may explore settlement with the lender before an auction is completed, subject to the lender’s approval and applicable legal requirements. Early action can be important because recovery proceedings may continue according to statutory procedures.
Where can I challenge SARFAESI recovery action?
An eligible borrower or aggrieved person may approach the Debt Recovery Tribunal (DRT) under Section 17 of the SARFAESI Act in accordance with the applicable legal provisions and limitation requirements.
What is an equitable mortgage?
An equitable mortgage is generally created through the deposit of title deeds with the lender, subject to the applicable legal requirements. It is commonly used in lending transactions involving immovable property.
What is a registered mortgage?
A registered mortgage is formally registered according to applicable registration and stamp-duty requirements. The precise documentation and registration requirements can vary depending on the transaction and applicable state law.
Can I redeem my mortgaged property before the sale is completed?
The right of redemption is governed by applicable law and the circumstances of the enforcement proceedings. Borrowers should act promptly and obtain appropriate legal advice where possession or sale proceedings have begun.
What is an acceleration clause in a mortgage loan agreement?
An acceleration clause may allow a lender, subject to the agreement and applicable law, to demand payment of the entire outstanding amount after specified events such as default.
What should I do after receiving a mortgage loan recovery notice?
Do not ignore the notice. Review the deadline, outstanding amount, security details, and legal basis of the action. You may also consider whether Mortgage Loan Settlement, restructuring, repayment, or appropriate legal remedies are relevant to your circumstances.
Mortgage Loan Settlement Assistance
Borrowers facing difficulty with a Mortgage Loan, Loan Against Property, or LAP Loan may require both financial and legal assessment before deciding how to proceed.
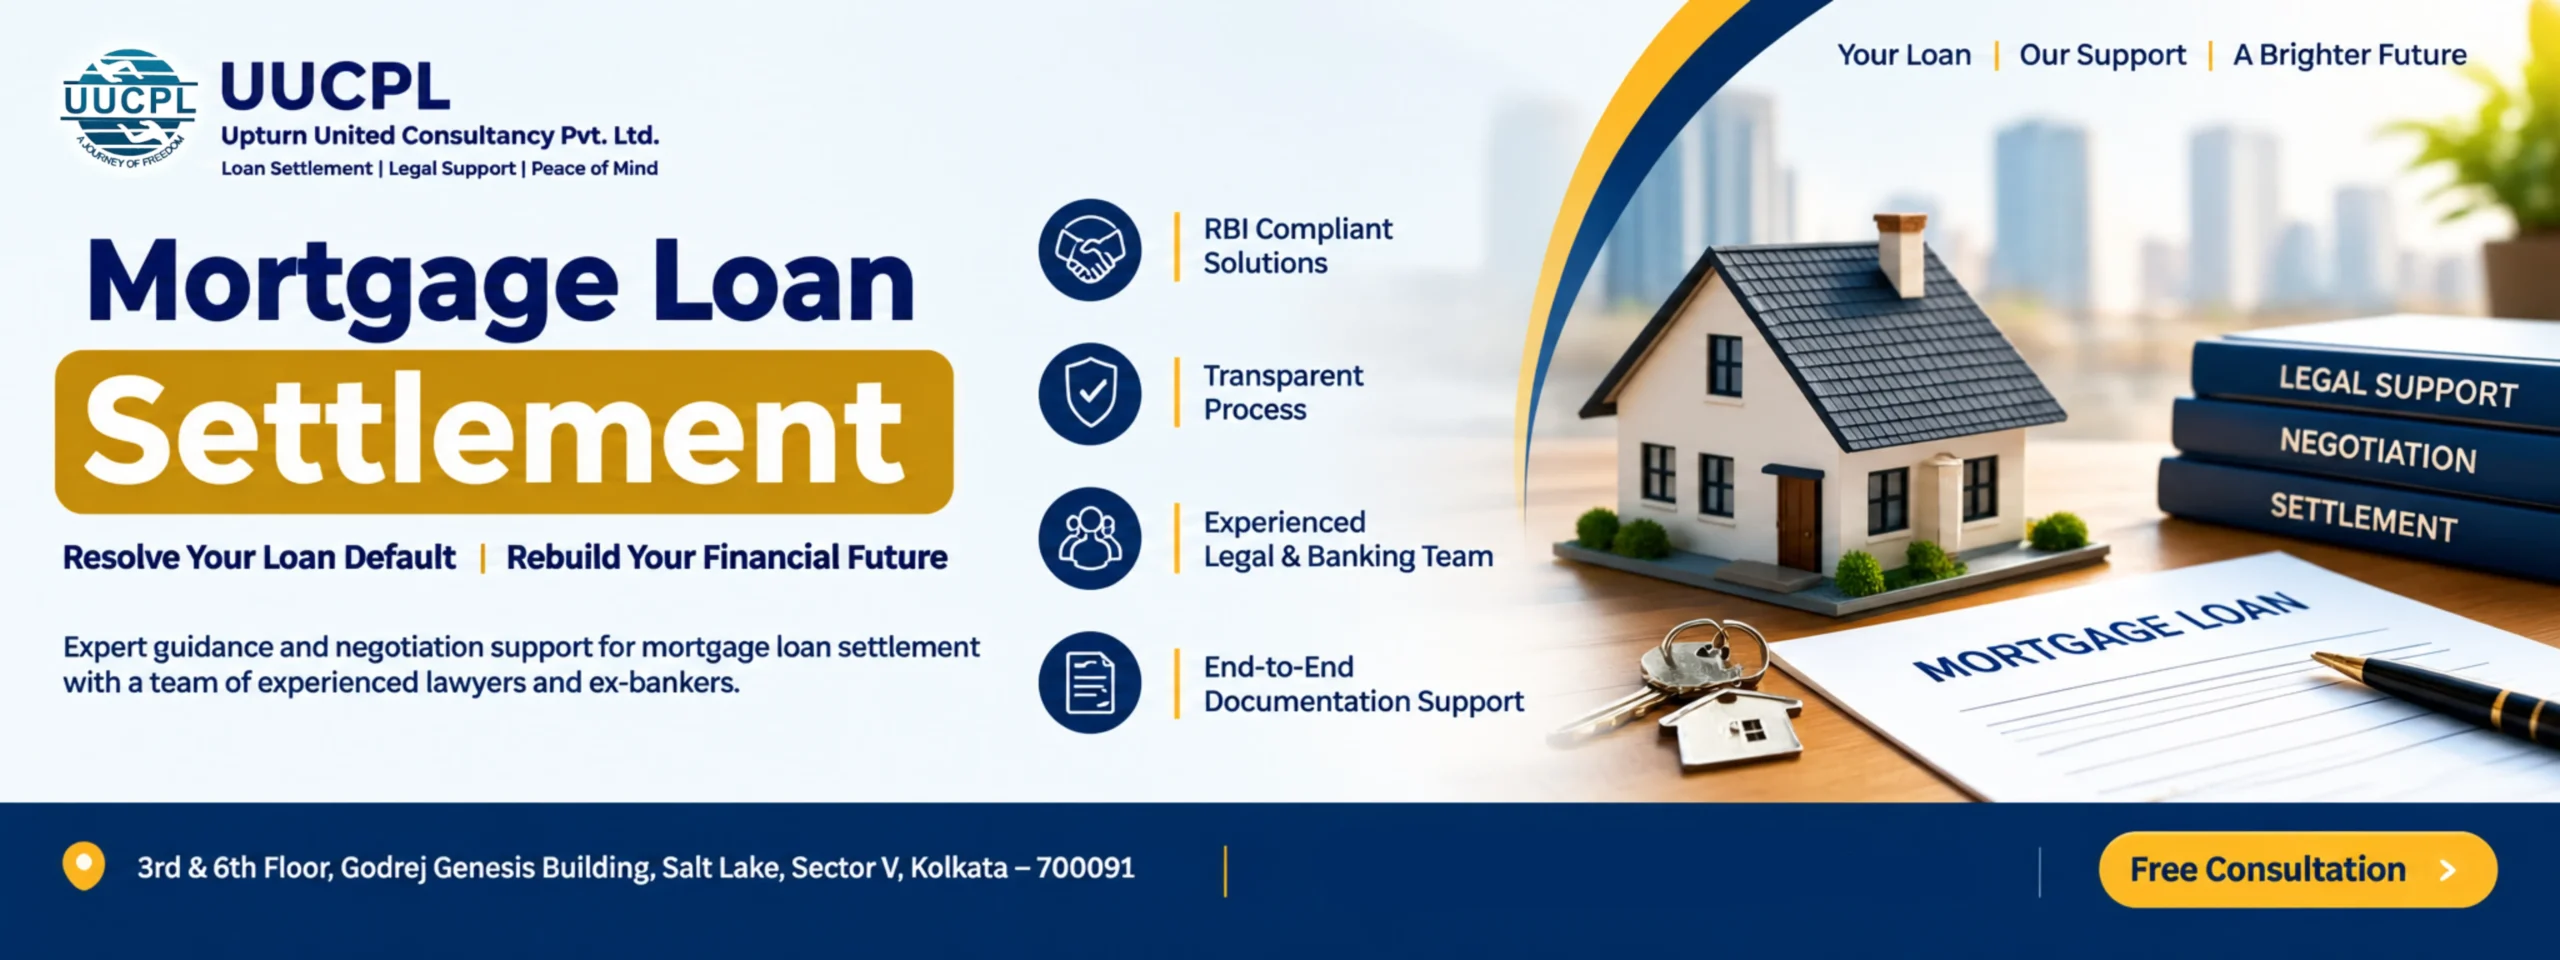
UUCPL provides consultancy and support relating to Mortgage Loan Settlement, Loan Against Property Settlement, loan settlement negotiations, documentation, and related recovery matters. The appropriate approach depends on the borrower’s financial position, lender, outstanding dues, property security, and current stage of recovery proceedings.
Disclaimer: UUCPL is an independent consultancy and is not a bank, NBFC, or lender. It does not provide loans or guarantee settlement outcomes. Services are limited to advisory, negotiation, and documentation support relating to applicable loan settlement matters.