
Home Loan Settlement in India: A Legal and Practical Guide
Struggling with an outstanding home loan can be stressful, especially when missed EMIs, recovery calls, or legal notices begin to affect your financial stability. Home Loan Settlement is one option that borrowers may explore when they are unable to repay the full outstanding loan amount due to genuine financial difficulties.
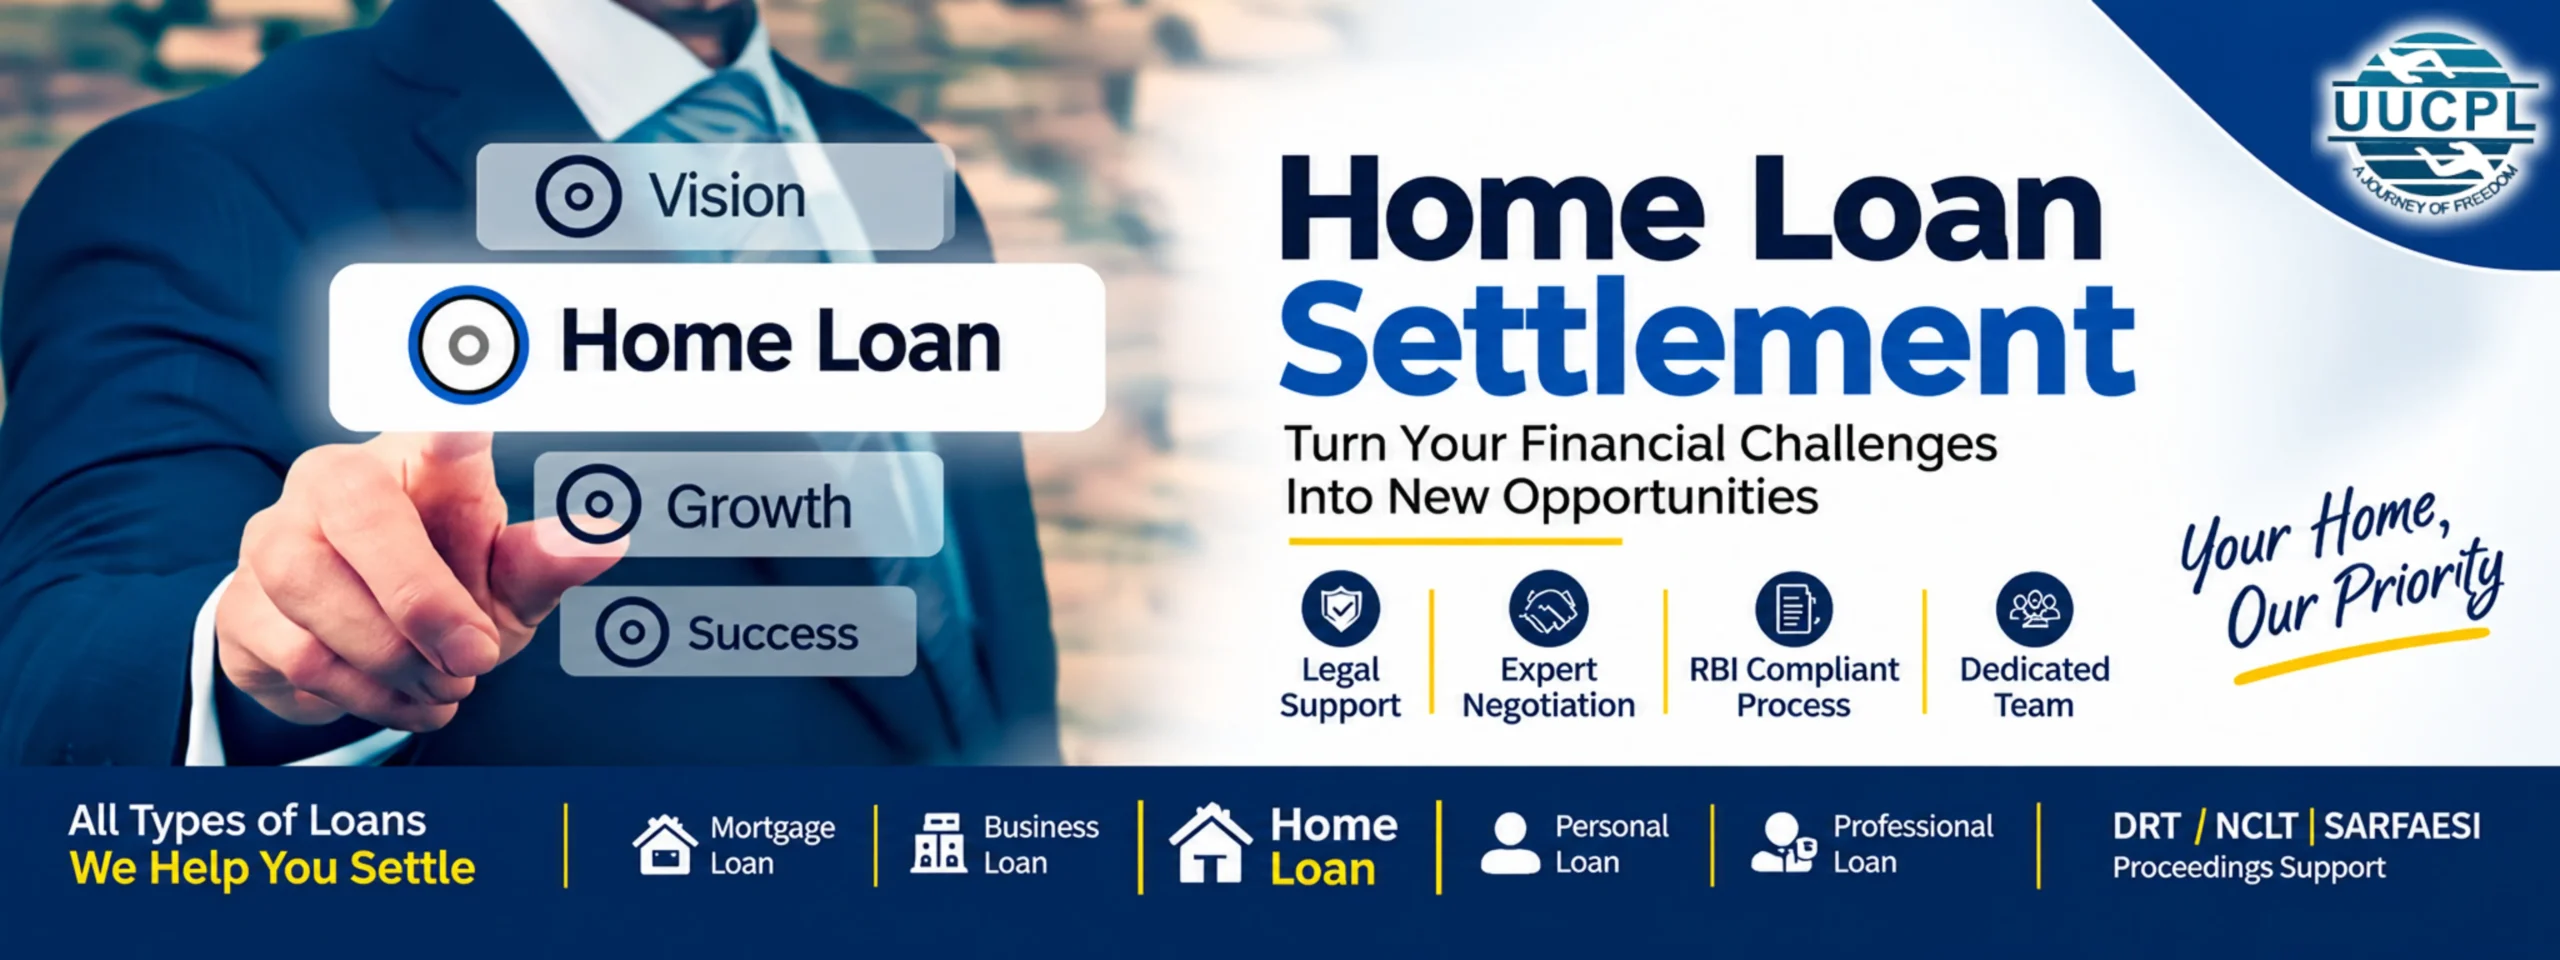
A Home Loan Settlement generally involves negotiating with the lender to resolve a defaulted home loan through a One-Time Settlement (OTS) arrangement, subject to the lender’s approval and applicable policies. A professional loan settlement agency may assist borrowers with case assessment, document review, lender communication, negotiation, and settlement documentation.
Understanding the Home Loan Settlement process is important before making any decision. Borrowers should also understand the possible impact on their CIBIL score, the consequences of home loan default, and legal processes such as SARFAESI proceedings and remedies before the Debts Recovery Tribunal (DRT).
What Is Home Loan Settlement?
Home Loan Settlement is a negotiated arrangement between a borrower and lender to resolve a defaulted home loan for an amount that may be lower than the total outstanding dues, subject to the lender’s approval.
A lender may consider a settlement proposal based on factors such as the borrower’s financial circumstances, outstanding dues, security value, repayment capacity, age of default, and recovery prospects.
Home Loan Settlement should not be understood as an automatic waiver of the outstanding loan. The final settlement amount and terms depend on the lender’s decision and applicable policies.
Home Loan Settlement in India: Understanding the Legal Framework
A home loan is one of the largest financial and legal commitments a borrower may undertake in India. While borrowers generally focus on EMIs, interest rates, and repayment tenure, the legal structure of the home loan agreement becomes particularly important when repayment difficulties arise.
The Home Loan Settlement process may involve financial negotiation as well as legal and documentation considerations. The mortgage created over the property, terms of the loan agreement, applicable recovery laws, and the stage of default can all influence the options available to the borrower.
This guide explains important aspects of Home Loan Settlement in India, including home loan default, NPA classification, SARFAESI proceedings, DRT remedies, borrower rights, CIBIL impact, and the general settlement process.
Understanding the Legal Structure of a Home Loan Agreement
A home loan agreement operates under the Indian Contract Act, 1872, alongside a mortgage created over the property under the Transfer of Property Act, 1882.
Most home loans are secured either through an equitable mortgage, created by depositing title deeds, or through a registered mortgage deed, depending on the lender and the property’s location.
The home loan agreement typically includes:
- Loan amount, tenure, and interest rate type.
- Security created through the mortgage over the financed property.
- Repayment schedule and EMI obligations.
- Prepayment and foreclosure terms.
- Events of default and their consequences.
- Insurance and property maintenance obligations.
- Dispute resolution and jurisdiction clauses.
Understanding these terms can help borrowers assess their position before considering Home Loan Settlement or other repayment options.
Laws Governing Home Loans in India
Several laws and regulations may apply to home loans and related recovery proceedings in India:
- Indian Contract Act, 1872 — governs the validity and enforceability of the loan agreement.
- Transfer of Property Act, 1882 — governs the mortgage created over the property.
- SARFAESI Act, 2002 — provides a legal framework for enforcement of security interests and recovery of dues in applicable cases.
- Recovery of Debts and Bankruptcy Act, 1993 (RDB Act) — governs proceedings before the Debts Recovery Tribunal (DRT) for banks and notified financial institutions.
- RBI’s Fair Practices Code and applicable Master Directions — provide requirements concerning transparency, disclosures, and fair recovery practices.
- Negotiable Instruments Act, 1881 (Section 138) — may apply where EMI cheques are dishonoured, subject to the facts and applicable legal requirements.
These legal provisions can become particularly relevant when a borrower is dealing with home loan default, recovery notices, SARFAESI action, or discussions concerning Home Loan Settlement.
Home Loan Settlement Process in India
The Home Loan Settlement process can vary depending on the lender, loan account, outstanding amount, financial circumstances of the borrower, and the stage of recovery proceedings.
A general Home Loan Settlement process may include the following stages:
1. Initial Consultation
The borrower’s loan details, outstanding dues, repayment history, and current financial circumstances are reviewed.
2. Case and Document Assessment
Relevant documents such as the loan agreement, account statements, notices, repayment records, and other supporting financial documents may be reviewed.
3. Financial Assessment
The borrower’s repayment capacity and financial circumstances may be considered while preparing a settlement proposal.
4. Negotiation With the Lender
The borrower or authorised representative may communicate and negotiate with the lender regarding a possible One-Time Settlement (OTS).
5. Settlement Proposal
The lender may evaluate the proposal based on its internal policies, outstanding dues, security value, recovery prospects, and other relevant factors.
6. Settlement Approval and Documentation
If the lender accepts the proposal, the agreed terms should be documented properly, including the settlement amount, payment schedule, and applicable closure requirements.
The exact timeline of the Home Loan Settlement process varies from case to case.
Key Legal Clauses Borrowers Should Review Carefully
Before pursuing Home Loan Settlement, borrowers should understand important clauses in their loan agreement.
Foreclosure and Prepayment Charges
Applicable RBI directions govern when lenders can levy prepayment or foreclosure charges, including specific rules concerning floating-rate housing loans taken by individual borrowers.
Default and Acceleration Clause
Depending on the loan agreement, a default may allow the lender to demand repayment of the entire outstanding loan rather than only missed instalments.
Cross-Default Clause
A default under one loan facility may have consequences for other facilities held with the same lender, depending on the contractual terms.
Assignment Clause
A loan agreement may allow the lender to assign or transfer certain loan rights to an Asset Reconstruction Company (ARC), subject to applicable law and contractual terms.
Understanding these clauses can help borrowers make informed decisions regarding Home Loan Settlement, restructuring, repayment, or other available options.
What Happens If I Default on a Home Loan in India?
When a borrower misses home loan payments, the account may eventually enter the lender’s recovery process. The following stages may become relevant:
- NPA classification — the account may be classified as an NPA after the applicable period of non-payment, generally 90 days under applicable RBI norms.
- Demand Notice — under Section 13(2) of the SARFAESI Act, the lender may issue a demand notice requiring the borrower to clear the specified dues within the statutory period.
- Borrower’s Objections — under Section 13(3-A), the borrower may raise objections, which the lender is required to consider and respond to in writing.
- Possession and Sale — where applicable statutory requirements are met, the lender may take steps under Section 13(4), including possession and sale of the secured property.
- DRT Remedy — a borrower may approach the Debts Recovery Tribunal (DRT) under Section 17 in accordance with the applicable statutory procedure.
- Redemption Rights — the borrower’s right of redemption is subject to applicable law and the stage reached in the enforcement and sale process.
- Surplus Proceeds — amounts recovered beyond the applicable outstanding dues, interest, and costs are subject to applicable legal requirements concerning surplus payment.
For borrowers facing these circumstances, Home Loan Settlement may be one of the options worth discussing with the lender, depending on the facts of the case.
Home Loan Settlement and SARFAESI Proceedings
When a secured home loan enters the recovery process, borrowers may receive a SARFAESI demand notice.
Under Section 13(2) of the SARFAESI Act, the lender may issue a demand notice requiring payment of the specified dues within the statutory period.
If the borrower is unable to clear the dues, further enforcement measures may follow in accordance with the Act.
In appropriate circumstances, borrowers may explore Home Loan Settlement with the lender while also understanding their applicable legal remedies.
Because the stage of SARFAESI proceedings can affect the available options, borrowers should carefully review any notice received and obtain appropriate legal or financial advice.
Borrower Rights Often Overlooked
Borrowers dealing with home loan recovery or Home Loan Settlement should understand their applicable rights and procedures, including:
- Right to receive relevant loan documents and enforcement notices.
- Right to understand the outstanding dues and applicable charges.
- Right to raise objections where permitted under applicable law.
- Protection against inappropriate or intimidating recovery practices under applicable guidelines.
- Right to pursue applicable remedies before the Debts Recovery Tribunal (DRT).
- Right to obtain information regarding the settlement terms before making payment.
- Right to receive appropriate settlement or closure documentation after fulfilling the agreed settlement conditions.
Does Home Loan Settlement Affect CIBIL Score?
Yes. Home Loan Settlement can affect your CIBIL score and credit history.
When a lender accepts a settlement for less than the full outstanding amount, the account may be reported as “Settled” rather than “Closed”, depending on the reporting and circumstances.
A “Settled” status can negatively affect a borrower’s credit profile and may make future loan or credit applications more difficult.
Therefore, borrowers should understand the potential CIBIL impact of Home Loan Settlement before accepting a settlement arrangement.
Home Loan Settlement vs Loan Restructuring
Home Loan Settlement and loan restructuring are different approaches.
In a settlement, the lender may agree to resolve the account for an amount lower than the total outstanding dues, subject to approval and applicable policy.
In restructuring, the borrower generally continues to repay the loan under modified terms, which may involve changes to the repayment schedule, tenure, EMI structure, or other applicable terms.
The appropriate option depends on the borrower’s financial circumstances, loan status, lender policy, and long-term repayment ability.
Frequently Asked Questions About Home Loan Settlement
1. What is Home Loan Settlement?
Home Loan Settlement is a negotiated arrangement between a borrower and lender to resolve a defaulted home loan for an agreed amount that may be lower than the total outstanding dues.
It is generally considered when a borrower is experiencing financial difficulty and is unable to repay the full outstanding amount.
A Home Loan Settlement agency may assist with case assessment, documentation, communication, and negotiation, depending on the services offered.
2. How does the Home Loan Settlement process work?
The Home Loan Settlement process generally involves:
- Initial consultation
- Loan account assessment
- Document verification
- Financial assessment
- Settlement proposal
- Negotiation with the lender
- Settlement approval
- Payment and settlement documentation
The exact process and timeline depend on the lender and the individual case.
3. Does Home Loan Settlement affect CIBIL?
Yes. A settlement may be reflected as “Settled” rather than “Closed”, which can negatively affect the borrower’s credit profile.
Before choosing Home Loan Settlement, borrowers should consider this potential impact alongside their overall financial circumstances.
4. What happens if I default on my home loan?
After the applicable period of non-payment, the loan may be classified as an NPA. Depending on the circumstances, the lender may issue a SARFAESI demand notice and initiate further recovery measures.
Borrowers may have applicable legal remedies and may also explore Home Loan Settlement with the lender.
5. Can Home Loan Settlement stop a SARFAESI auction?
A settlement may potentially resolve the outstanding dues if the lender agrees to the settlement and the borrower fulfils the agreed conditions. However, Home Loan Settlement does not automatically stop SARFAESI proceedings.
The borrower should review the current stage of the proceedings and obtain confirmation of the lender’s settlement terms before making assumptions about the status of enforcement action.
6. Can I approach DRT for a home loan recovery matter?
Depending on the circumstances and applicable statutory requirements, a borrower may approach the Debts Recovery Tribunal (DRT) under the relevant provisions of the SARFAESI Act.
Legal remedies depend on the facts, notices received, and stage of proceedings.
7. Can the bank sell my home loan to an ARC?
Depending on the loan agreement and applicable law, a lender may assign or transfer certain loan rights to an Asset Reconstruction Company (ARC).
Borrowers should carefully review any communication received regarding assignment or transfer of their loan account.
8. How long does Home Loan Settlement take?
There is no fixed timeline for every Home Loan Settlement case.
The process may depend on:
- Lender’s internal process
- Outstanding loan amount
- Financial condition of the borrower
- Documentation
- Loan account status
- Negotiation process
- Whether SARFAESI or other recovery proceedings have started
Earlier assessment and proper documentation may help borrowers understand their available options sooner.
9. What should I check before choosing a Home Loan Settlement agency?
Before selecting a Home Loan Settlement agency, borrowers should check:
- Experience with home loan cases
- Legal and financial expertise
- Transparency regarding fees
- Explanation of CIBIL impact
- Documentation process
- Communication procedure
- Experience with lender negotiations
- Handling of recovery notices and legal proceedings
- Clear explanation of the services being provided
Borrowers should be cautious of anyone guaranteeing a fixed settlement amount or promising an automatic loan waiver.
10. Is Home Loan Settlement confidential?
Borrowers should review the organisation’s privacy practices before sharing financial documents and personal information.
A professional Home Loan Settlement service provider should clearly explain how client information, loan documents, and financial details are handled during consultation, assessment, negotiation, and documentation.
Conclusion
Home Loan Settlement can be an option for borrowers facing genuine financial difficulties and struggling to repay their outstanding home loan. However, settlement is not an automatic waiver and depends on the lender’s approval, applicable policies, the borrower’s circumstances, and the stage of the loan account.
Before proceeding with Home Loan Settlement in India, borrowers should understand the possible impact on their CIBIL score, the consequences of home loan default, the SARFAESI process, applicable DRT remedies, and the terms of the proposed settlement.
A clear understanding of the Home Loan Settlement process, proper documentation, and transparent communication with the lender can help borrowers evaluate their available options more effectively.